


Any company with financial reporting periods starting on or after 1 January 2003 has to comply with Singapore’s accounting standards – this is an ACRA requirement. They are known as SFRS(I)s and are the same as IFRS accounting.
Reporting must be done according to the rules defined by the Accounting and Corporate Regulatory Authority. This standard is shared by all; the rule provides consistency; it helps the user to trust the statements.
Everyone who is banking with any of the financial institutions in Singapore will not be eligible under Model 1 agreement 1 with PWC Tax Summaries on Foreign Account Tax Compliance Act (FATCA), should they decide to do so.
This is an article about the important functions of the Singapore Accounting Standards, such as the regulatory environment, the opportunities for a business in complying with it, and the challenges faced by it in doing so.
 Key Takeaways
- Singapore Accounting Standards (SFRS) align closely with IFRS. SFRS mandates IFRS compliance for listed companies and offers it as an option for others.
- Key Singapore accounting standards like SFRS for Small Entities and Charities provide simplified reporting for different sectors, reducing complexity while ensuring regulatory adherence.
- Benefits of compliance with SFRS include enhancing investor confidence, supporting informed decision-making, and helping businesses avoid penalties, ensuring long-term financial stability.
- Accounting Software by ScaleOcean Atlas simplifies financial management, automating accounting processes, ensuring SFRS compliance, and providing real-time financial insights for businesses in Singapore.

What are Accounting Standards in Singapore?
Accounting standards in Singapore are a set of financial reporting principles that guide how businesses record, measure, and present financial information. These standards are established by the Accounting Standards Committee (ASC) under the Accounting and Corporate Regulatory Authority (ACRA) to ensure transparency, consistency, and reliable financial reporting.
Singapore’s financial reporting frameworks are closely aligned with the International Financial Reporting Standards (IFRS). Singapore Financial Reporting Standards (International), or SFRS(I), are mandatory for Singapore-incorporated companies listed on the Singapore Exchange, while non-listed companies may adopt them voluntarily.
Other standards, such as FRS 1 for financial statement presentation and FRS 115 for revenue recognition, provide guidance on specific accounting practices.
Furthermore, these standards generally follow the accrual accounting principle, which recognizes income and expenses when transactions occur rather than when payments are received or made. Together with requirements under the Companies Act, they help businesses maintain consistent financial records and prepare reliable financial statements.
To simplify compliance, businesses can use the best accounting software in Singapore that supports Singapore’s reporting requirements, accurate transaction recording, and financial statement preparation.
What are the Main Singapore Financial Reporting Standards, and Who Must Follow Them?
Financial transparency and accuracy are paramount virtues in Singapore’s business landscape, and compliance with accounting standards is a testament to that. The significance of Accounting in Singapore is that it plays a crucial role in ensuring the reliability of financial reports, which are also comparable and adhere to international standards. Now, the whole explanation:
1. Singapore Financial Reporting Standards (SFRS)
Singapore’s main accounting system is similar to International Financial Reporting Standards (IFRS), called SFRS. It promotes uniformity, clarity, and standardization in financial reporting among different industries. This includes SFRS tools like an existing purchase journal, etc., with many companies having to comply with SFRS to be able to transact on the books as a proper record to maintain the reliability of transactions.
These Standards cover the accounting for leases, financial instruments, and revenue recognition. Compliant with the global financial landscape and meaningful, SFRS will strengthen credibility, which may help facilitate cross-border business operations.
Who must follow them? Singapore-incorporated companies generally prepare financial statements under an applicable SFRS framework. For example, SGX-listed companies use SFRS(I), while many private companies apply FRS.
2. SFRS for Small Entities (SFRS for SE)
SFRS for SE (Small Entities) refers to a simple financial reporting system for small and medium-sized unaccountable entities (SMEs). It streamlines the processes without violating the principles of concepts like fair value accounting and accrual-based accounting.
SMEs are helped to prepare financial statements that are effective and will at least reduce compliance costs, since they will ensure that reports are credible with credible information and comply with Singapore’s regulatory requirements.
Who can follow them? Small businesses without public accountability that meet the eligibility criteria may choose this simplified framework. For example, a qualifying privately owned retail or consulting company may adopt SFRS for SE.
3. SFRS for Charities
Financial Reporting is the focus of the SFRS for Charities, which is being developed for non-profit organizations. This sets the guidelines for the recognition of income, the responsibilities for managing financial funds, and also the accountability in financial statements, as charities are funded primarily from income from donations and grants.
With the SFRS for Charities, non-profits will be able to set up a trust, improve governance,ce and demonstrate good financial management to better leverage their resources to support their communities.
Who can follow it? Eligible registered charities and Institutions of a Public Character (IPCs) in Singapore may use CAS. For example, charitable foundations and community welfare organisations can apply it when preparing financial statements.
4. Financial Reporting Standard (FRS) – Financial Instruments
This standard guides accounting for items that are recognized, measured, and reported as financial instruments in the financial statements, including loans, bonds, and derivatives. It gives guidance on the classification of assets and liabilities, the determination of fair value, and hedges.
Correctly accounting for financial instruments is a necessary means of correctly reflecting the financial situation and managing the investment risks of a company. Compliance will also bring greater transparency to the overall picture of a company’s financial health and risk exposure, and create a clear framework for investors to make better investment decisions and improve corporate governance, enabling them to take sustained action on the standard.
Businesses can benefit from accounts payable software to ensure accuracy in these processes. that automates the transaction tracking process while making sure of adherence to financial reporting standards for improved corporate governance and investment decisions. Record it in the financial statements when it has been earned.
Who must follow it? Businesses applying FRS that hold financial assets or liabilities within the standard’s scope must follow FRS 109. For example, companies managing investments, loans, or derivative contracts must account for these instruments appropriately.
5. Financial Reporting Standard (FRS) – Revenue from Contracts with Customers
This standard enables entities to consistently recognize revenue streams through customer contracts, with the shared objective of delivering a consistent framework for doing so, irrespective of the industry or entity. Entities should determine control of goods or services when they transfer them to customers, not when they receive payment.
Companies use a five-step model: recognise a contract, define the performance obligations, determine the transaction price, allocate the transaction price, and recognise revenue when the performance obligations are met.
This will enable organizations to prepare accurate financial statements, minimise financial reporting inconsistencies, and create transparency for shareholders and investors to more effectively check the profitability of a company and its economic viability.
Who must follow it? Companies reporting under FRS must apply FRS 115 to customer contracts within its scope. For example, construction firms, software providers, and service companies use it to recognize revenue as contractual obligations are fulfilled.
6. Financial Reporting Standard (FRS) – Leases
The FRS on leases introduces uniform methods for businesses to account for leases, meaning that its lessees record the vast majority of leases as a right-of-use asset and a corresponding lease liability. This change is to make it clearer to recognize lease commitments in the financial statements.
In addition to this, businesses are required to provide further disclosure on leases, such as future obligations, lease-related costs, etc. In general, the standard gives better financial transparency and improves the comparability of investments to make evaluations of a firm’s financial commitments easier.
Who must follow it? Businesses applying FRS that enter into lease arrangements within the scope of FRS 116 must follow its requirements. For example, retailers renting commercial premises or logistics companies leasing vehicles must account for these commitments.
7. Financial Reporting Standard (FRS) – Inventories
It provides a far better representation of a company’s underlying financial condition. It is much better than balancing the bank statements in terms of tracking business activities because the moment-by-moment tracking lets all those concerned with keeping the books see it.
The concept of the cost of inventories under the Financial Reporting Standard (FRS) guides the measurement and reporting of inventory costs, so it will be possible to report inventories at valid prices. To prevent overstatement of inventories, companies need to account for inventories at either cost or NRV.
Consistency in valuation is provided within the standard, allowing for cost formulas such as First-In, First-Out (FIFO) and weighted average cost. Companies that adhere to this standard will have the right recording practices, utilise inventory effectively, and provide solid data for stakeholders, which will aid them with cost management and regulatory compliance.
Who must follow it? Companies applying FRS that hold inventory within the scope of FRS 2 must comply with its valuation requirements. For example, manufacturers, wholesalers, and retailers use this standard to report raw materials, merchandise, and finished goods.
Key Principles and Requirements of SFRS
Financial transparency is the backbone of Singapore’s economy, and the Singapore Financial Reporting Standards ensure that businesses maintain consistency and accuracy in their financial reporting. Here are the key principles that shape financial management examples and reporting under the Singapore accounting standards:
1. Accrual Accounting
Accrual-based records recognise transactions when they occur, rather than when cash is received or paid. With AI accounting, the key point is when the transaction is finalized, not when the physical goods are delivered.
This approach provides a much better indicator of a company’s true financial health. It gives everyone involved a running picture of how their business is doing, much more accurate than gaining a picture of the business based on bank balances alone.
2. Comparability
The financial information of a company should be consistent and comparable with that of similar organizations. This principle guarantees that the data for accounting purposes will be useful for analysis and decision-making.
SFRS allows stakeholders to assess financial metrics examples over time and in comparison to competitors. This requires businesses to use consistent accounting and enables the users, who are interested parties, to compare the financial presentation over time and with other competitors.
3. Relevance
Financial reports should contain information that is meaningful and can impact decision-making. Data should give predictive insights as well as confirm past performance and support informed decisions.
Financial Reports are mandated by the Singapore Financial Reporting Standards (SFRS) to contain the necessary information that may impact stakeholders’ economic decisions. By customizing reports to meet the needs of investors and regulators, businesses enhance financial communication and build trust with key stakeholders.
4. Verification
Verification verifies that financial statements contain reliable information, which enables investors and stakeholders to judge the financial health of a company. This dictates that there must be financial information within financial reports that can be used to verify that expectations have been met or future financial results can be predicted.
This principle makes it easier to make good faith accounting claims, thereby allowing regulators, auditors, and investors to thoroughly check companies’ claims about their financial performance. An accurate, verified financial statement can articulate a business’s stability and prospects, which can assist in enhancing monetary decision-making.
5. Faithful Representation
To reflect a company’s financial position, performance, and cash flows in financial statements, financial statements must be made in a way that is free of frivolous reports or specious representations designed to enhance a company’s image. This principle is to ensure that the information is complete in nature, neutral,l and free from material errors so that the stakeholders can make an informed choice.
The companies must make truthful reports in every transaction. They help them write financially accurate stories without bias or error, and so promote trust and eliminate misleading misstatements from their report at the end.
6. Prudence
This principle requires businesses to exercise caution when recognizing revenues and expenses, ensuring that financial statements do not overstate profits or assets. Prepaid expenses are a good example, as businesses must carefully account for them and recognize them only when the benefit is received.
Additionally, the principle encourages companies to account for potential losses and liabilities as soon as they are foreseeable. Revenues, on the other hand, should only be recognized when they are assured, helping to maintain accuracy and prevent premature financial reporting.
7. Fair Value Measurement
SFRS also ensures that financial assets and liabilities are recorded at their current market value rather than historical cost. This principle allows businesses to reflect the true worth of their financial instruments, investments, and assets in financial statements.
Under SFRS, fair value is calculated using current market conditions, independent appraisals, or valuation models. This approach makes sure that the numbers reflect reality and provide a transparent view of a company’s value.
8. Going Concern
The going concern principle assumes that a business will continue operating for the foreseeable future unless there is evidence to the contrary. By adhering to the going concern principle, businesses build confidence among creditors and investors, reinforcing trust in their financial sustainability and ability to meet future obligations.
Additionally, businesses that prioritize ESG (Environmental, Social, and Governance) criteria demonstrate a commitment to long-term sustainability, further enhancing trust and credibility with stakeholders.
9. Clarity and Comprehensibility
SFRS’s focus on understandability ensures financial statements are clear for everyone, especially investors. Information should be shared in a straightforward way, keeping things simple and avoiding any confusing or vague language.
This principle is all about transparency. By keeping figures and notes clear, even those with basic financial knowledge can easily grasp the data. It helps users reliably check a company’s health and make much smarter decisions.
10. XBRL Filing and Audits
Companies in Singapore that are required to submit financial statements to ACRA must follow the applicable XBRL reporting requirements. This digital format helps standardize financial information, improve transparency, and support regulatory reviews.
Additionally, businesses that do not qualify for audit exemptions must have their financial statements audited in accordance with Singapore Standards on Auditing (SSA). Eligible small companies may be exempt, depending on their revenue, assets, and employee count.
Benefits of Compliance with Accounting Standards
Compliance with SFRS regulations is critical for firms seeking financial stability and long-term viability. Compliance promotes stakeholder trust and long-term corporate growth in addition to meeting legal requirements. Here are the primary benefits of conforming to Singapore accounting standards:
1. Transparency and Investor Confidence
Adhering to Singapore Accounting Standards increases financial transparency, which makes businesses more appealing to investors. Accurate financial reporting fosters trust and facilitates access to investment opportunities, while also supporting environmental, social, and governance initiatives that enhance long-term sustainability.
Investors and stakeholders use standardized financial statements to assess a company’s profitability and risks. Compliance also assures consistency in reporting, allowing organizations to compete effectively in both domestic and international markets.
2. Regulatory Compliance and Avoidance of Sanctions
Following financial reporting standards helps businesses meet regulatory requirements, so avoiding penalties or legal action from authorities. Singapore’s Accounting Standards Council (ASC) imposes tight requirements to ensure that all organizations comply with financial regulations.
Noncompliance can lead to financial penalties, reputational loss, and operational disruptions. Businesses that obey regulations can run effectively and avoid unnecessary legal issues.
3. Improved Business Decision-Making
A well-structured accounting system allows organizations to monitor financial performance, plan future investments, and improve operational efficiency. Compliance with financial reporting standards provides management with reliable data for identifying revenue patterns, cost-cutting options, and investment opportunities.
Businesses can use trustworthy financial information to accomplish strategic planning, optimize resource allocation, and efficiently minimize financial risks.
Compliance and Regulatory Framework in Accounting Standards in Singapore
Singapore’s strong financial ecosystem relies on a well-structured compliance and regulatory framework to uphold transparency, accuracy, and credibility in accounting practices. Below are the crucial elements of the Singapore accounting standards regulatory framework that businesses must adhere to.
1. The Accounting Standards Council Singapore (ASC)
The Accounting Standards Council (ASC) serves as the main authority for the creation and upkeep of SFRS. Formed under the Accounting Standards Act, ASC guarantees that financial reporting adheres to global best practices, particularly the International Financial Reporting Standards (IFRS).
The council frequently updates and amends standards to stay aligned with international financial trends and changing business landscapes. Adhering to ASC standards is compulsory for all businesses in Singapore, fostering transparency and uniformity in financial statements across various sectors.
2. Companies Act and Financial Reporting Obligations
The Companies Act, overseen by the Accounting and Corporate Regulatory Authority (ACRA), requires all companies in Singapore to adhere to SFRS when preparing their financial statements. Businesses must keep precise records, file annual financial reports, and guarantee that their statements accurately reflect their financial position.
Certain entities, including publicly traded companies and large private firms, are also required to undergo independent audits to verify their compliance. Noncompliance with financial reporting requirements may lead to penalties, fines, or legal repercussions.
3. Role of the Accounting and Corporate Regulatory Authority (ACRA)
ACRA in Singapore is the regulatory authority responsible for corporate governance and financial compliance in Singapore. It upholds the Companies Act and ensures that companies follow SFRS in their financial statements, including the accurate reporting of accounts receivable. ACRA performs audits, investigations, and compliance assessments to identify any errors or fraudulent actions in corporate financial statements.
The company also offers guidelines and resources to assist businesses in meeting regulatory obligations. By enforcing accounting standards and imposing penalties for non-compliance, ACRA is essential in preserving the integrity and credibility of Singapore’s financial environment. Businesses must remain informed about ACRA’s regulations to maintain compliance.
4. Singapore Exchange (SGX) Financial Reporting Requirements
Companies that are publicly listed in Singapore are obligated to adhere to additional reporting standards established by the Singapore Exchange (SGX). SGX requires that these listed entities submit regular financial statements that align with SFRS and disclose significant financial information to their investors.
These firms are also required to comply with stringent corporate governance practices, promoting transparency and accountability in their financial reporting. Furthermore, SGX mandates that listed companies engage external auditors for independent evaluations of their financial status.
5. Audit and Assurance Requirements
Auditing plays a vital role in Singapore’s framework for accounting compliance. Companies that surpass certain revenue or asset limits are required to undergo statutory audits carried out by licensed auditors registered with ACRA.
The audit process verifies that financial statements are accurate, reliable, and aligned with SFRS. Using tax preparation software can streamline the audit process by ensuring accurate tax data and simplifying the preparation of financial statements for review.
Singapore companies that are publicly traded, large private enterprises, and financial institutions face strict audit regulations. External auditors evaluate financial documents for errors, fraud, or discrepancies. By following audit regulations, companies boost transparency, enhance financial credibility, and build investor trust in their operations.
6. Tax Compliance and Reporting under the Inland Revenue Authority of Singapore (IRAS)
The IRAS oversees corporate tax compliance, ensuring that businesses accurately report their financial information for tax evaluation. Companies are required to prepare their financial statements following SFRS guidelines to appropriately calculate their taxable income.
Additionally, IRAS enforces regulations related to Goods and Services Tax (GST), withholding tax, and transfer pricing to deter tax evasion. Companies that do not adhere to tax reporting regulations may be subjected to audits, fines, or legal proceedings.
7. Enforcement Actions and Penalties for Non-Compliance
Robust enforcement measures ensure that companies comply with SFRS and regulatory standards. Organizations that do not meet these requirements may incur fines, face legal action, or encounter operational restrictions. ACRA, IRAS, and SGX perform regular compliance assessments to detect financial inaccuracies, fraudulent behaviors, or governance issues.
In extreme situations, companies that are not compliant could face monetary penalties, revocation of business licenses, or removal from the stock market. By implementing compliance through audits and investigations, Singapore’s regulatory bodies maintain financial integrity and corporate responsibility.
To support compliance and regulators in the accounting process, businesses can implement ERP software for financial accounting that helps standardise reporting, maintain accurate records, and ensure ongoing compliance.
8. Annual General Meeting (AGM) Requirements
In Singapore, holding an AGM is a must to stay compliant with the Companies Act. It’s a great chance for shareholders to get together, review how the business is doing, and look over the latest financial statements and key decisions.
You’ll need to hold your AGM within six months of your financial year-end. This keeps your governance on track, giving stakeholders a clear space to discuss the company’s health and make smart, informed choices for the future.
9. Maintenance of Statutory Records
Under Singapore’s accounting standards, businesses need to keep official records like shareholder and director registers. These files must be kept accurate and ready for inspection by authorized people whenever they need to check them.
Keeping these records updated is a big part of good corporate governance. It’s not just about rules, but it’s also about being transparent and proving that your company meets its legal obligations to regulators and stakeholders alike.
10. Filing of Annual Returns
Filing annual returns is a must for Singapore companies to stay in the clear. These filings share fresh updates on directors, shareholders, and finances, making sure everything is transparent and easy for everyone to see.
You’ll need to file your returns with ACRA within a month of your AGM. Using ScaleOcean Atlas can streamline this process by automating data management, ensuring accurate and timely filings, and helping you stay compliant with local standards for enhanced business transparency.

Challenges in Adhering to Accounting Standards
Compliance with accounting standards is an essential part of a Singaporean company’s financial transparency and compliance. However, this process often raises some issues that can make it difficult for businesses to stay on track. Here are some of the major issues that companies face:
1. Complexity of Regulations and Periodic Updates
Singapore Financial Reporting Standards are frequently updated, requiring organizations to keep educated and modify their accounting practices accordingly. These upgrades can be complex, making it difficult for businesses to completely comprehend and implement changes successfully.
Because of this, many firms find it tough to make sure their statements match the latest rules. This can lead to a gap in their reporting, which unfortunately puts the business at risk of falling out of compliance.
2. Resource and Expertise Limitations
Many organizations lack the in-house ability to handle complex financial reporting standards, which leads to compliance issues. This shortage of trained specialists can lead to inefficiencies and missed deadlines for submissions.
Small to medium-sized businesses (SMEs), in particular, may lack the resources to hire expert accountants, raising the risk of financial reporting errors or delays.
3. Risk of Human Error in Manual Processes
Manual accounting processes increase the risk of errors, which can lead to noncompliance and financial discrepancies. Relying on spreadsheets and paper records can make it challenging to track real-time updates or changes.
Without the best invoicing software, businesses are more prone to inconsistencies in financial reporting, which can result in compliance issues or missed tax deadlines. Automating these processes helps ensure accuracy and timely reporting, reducing the risk of violations.
Adhering to Singapore’s Accounting Standards With Accounting Software by ScaleOcean Atlas
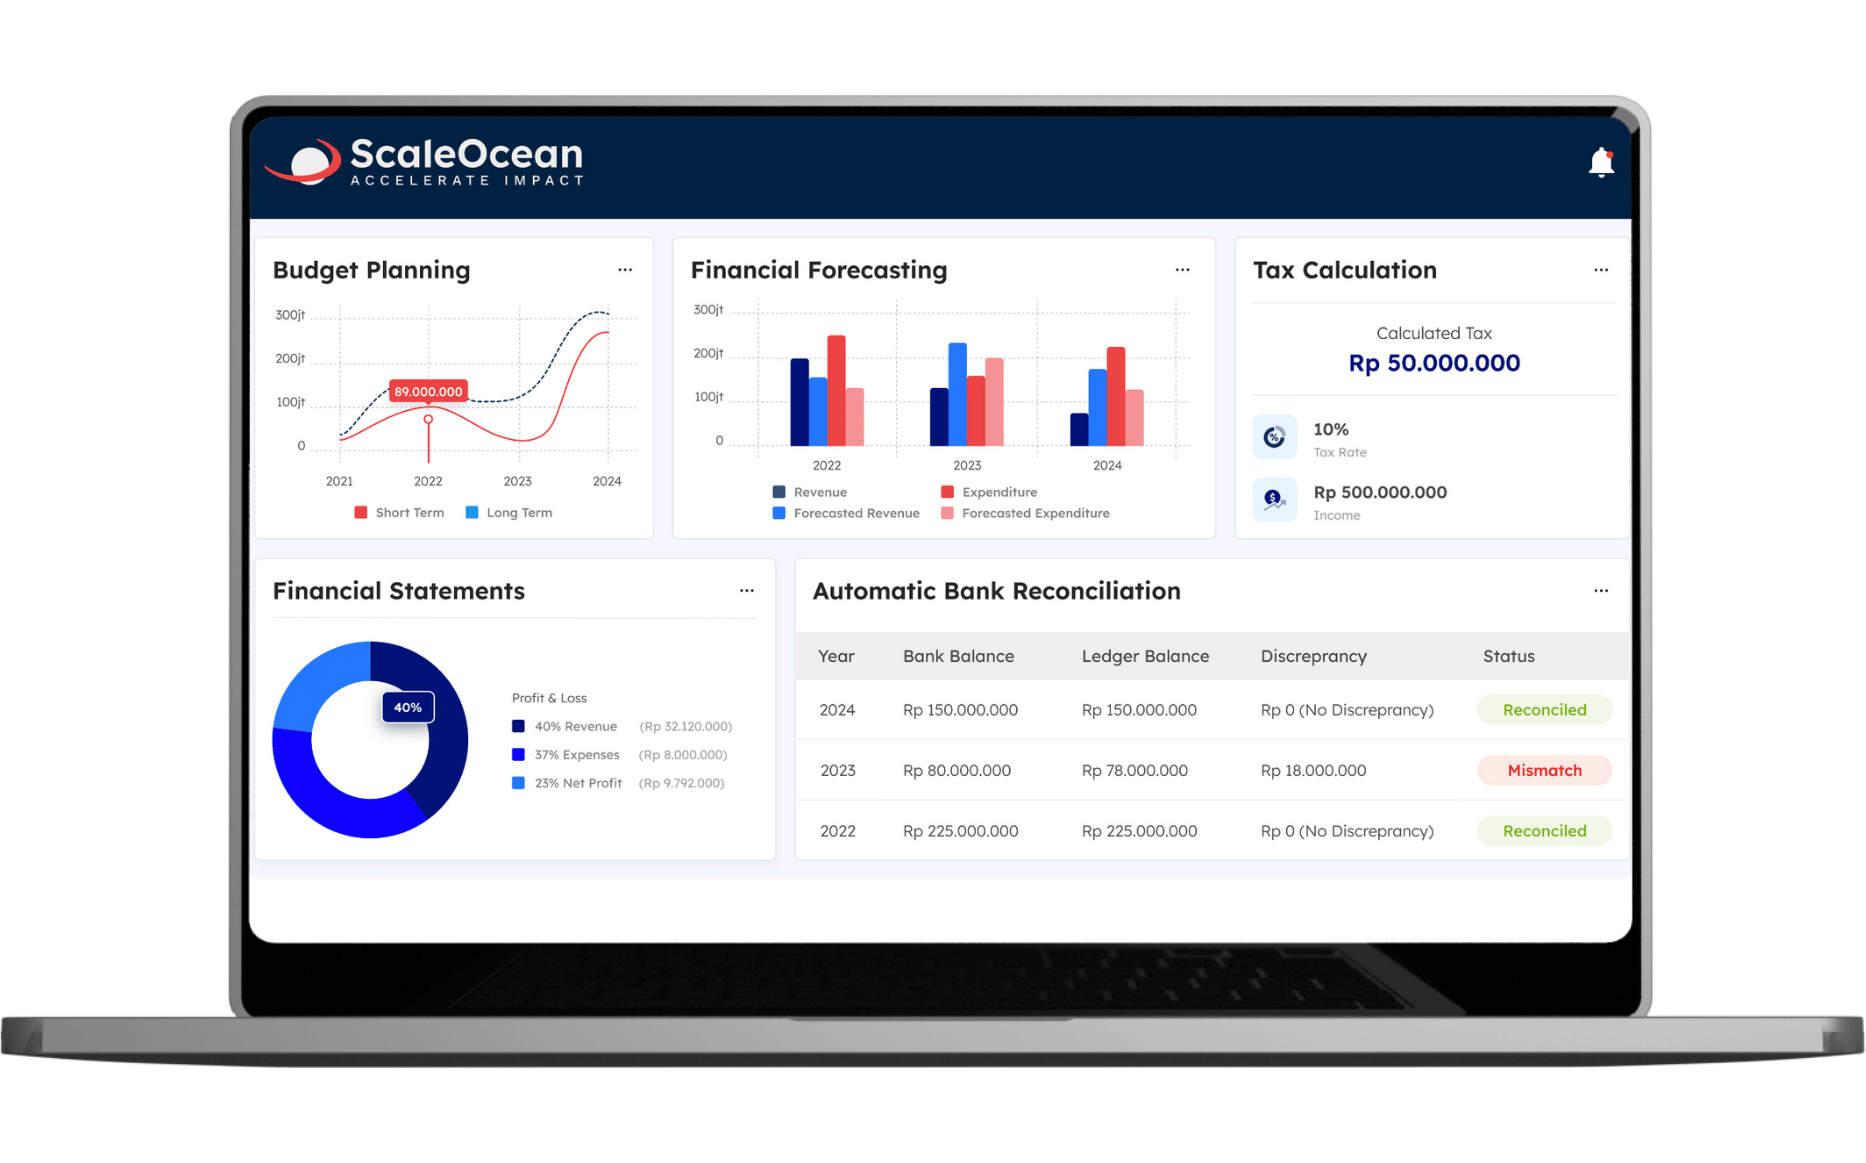
Accounting Software by ScaleOcean Atlas offers a comprehensive accounting software solution that streamlines financial processes and improves compliance for Singapore enterprises. With its user-friendly interface and sophisticated functionality, it reduces accounting difficulties while ensuring firms meet regulatory compliance.
ScaleOcean offers comprehensive ERP solutions that are fully eligible for the CTC grant up to 75% of funding, helping businesses streamline their financial management procedures. With its user-friendly interface and advanced features, ScaleOcean Atlas enhances efficiency and ensures seamless project and cost management.
So here are the key modules for ScaleOcean Atlas:
- Compliance with SFRS: ScaleOcean Atlas ensures compliance with Singapore Accounting Standards, making it easier for businesses to meet financial regulations.
- Automation of Accounting Processes: Automated financial reporting reduces errors and enhances accuracy, improving overall efficiency.
- Real-Time Financial Reporting: With real-time analytics, businesses gain better insights into financial performance, enabling data-driven decision-making.
- Scalability and Flexibility: The ScaleOcean Atlas platform adapts to the needs of both small businesses and large enterprises, offering scalable solutions.
- Integration with Other Business Systems: Seamless integration with ERP, HR, and inventory management systems enhances operational efficiency.
- Local Customer Support: With dedicated Singapore-based support, businesses receive timely assistance in managing their accounting needs.
Case Studies: Implementation of ScaleOcean in Singaporean Companies
To better understand the practical impact of ScaleOcean, let’s explore how it has been successfully implemented in different types of businesses in Singapore. These case studies showcase the software’s ability to address specific challenges and improve financial management across various industries.
1. Case Study 1: Manufacturing Company
A Singapore-based manufacturing company used ScaleOcean Atlas to automate financial reporting, saving substantial time and effort on human data entry. By automating their accounting operations, they reduced errors caused by human input, resulting in better accuracy and reliability in their financial reports.
The solution also allowed the company to retain complete compliance with Singapore’s demanding accounting standards, easing regulatory reporting and ensuring timely financial statement submission. This resulted in increased transparency and better decision-making throughout the company, particularly in its manufacturing processes.
2. Case Study 2: Retail Business
A retail company used ScaleOcean Atlas to seamlessly combine its financial data and inventory management system, resulting in a unified view of its operations. This integration improved the company’s cash flow by offering real-time visibility into financial and inventory data, allowing for more informed purchasing decisions and better stock management.
Furthermore, the automation of financial operations resulted in less manual work, allowing the retail sector to function more efficiently and focus on development prospects. ScaleOcean Atlas’s real-time reporting also enabled the company to respond rapidly to market developments while improving operational efficiency.
Conclusion
Understanding and adhering to Singapore Accounting Standards is critical for organizations to ensure financial transparency and regulatory compliance. Compliance enables firms to make educated, strategic decisions, which are critical for long-term success. Companies that remain compliant can avoid costly penalties while also increasing their market trust.
ScaleOcean Atlas simplifies accounting operations, ensuring organizations fulfill compliance standards while enhancing overall productivity. The software provides vital financial data to firms, allowing them to streamline their operations and reduce compliance concerns.
ScaleOcean provides a free consultation with our team of experts to businesses in Singapore wishing to improve their accounting practices, allowing you to see how our solutions may streamline your processes and help your business grow.
FAQ:
1. What is the difference between SFRS and IFRS?
SFRS and IFRS are highly aligned, with SFRS(I) being nearly identical to IFRS. Issued by Singapore’s ACRA, SFRS(I) follows the IFRS set by the IASB but includes local adaptations for compliance with Singapore’s corporate and tax regulations. These adjustments ensure relevance to the country’s financial reporting landscape.
2. What are Singapore Financial Reporting Standards (SFRS)?
Singapore Financial Reporting Standards (SFRS) set the guidelines for financial reporting, ensuring transparency and consistency. Based on IFRS with local modifications, SFRS follows the accrual accounting method, where transactions are recorded when they occur, not when payment is received, providing a more accurate financial position of businesses.
3. Who sets accounting standards in Singapore?
The Accounting Standards Council (ASC) sets accounting standards in Singapore. Established under the Accounting Standards Act 2007, it replaced the Council on Corporate Disclosure and Governance (CCDG) in developing SFRS and SFRS(I). ASC ensures alignment with international standards while adapting to Singapore’s regulatory and business environment.
4. Is IFRS 17 an accounting standard?
Yes, IFRS 17 is the global accounting standard for insurance contracts, replacing IFRS 4 in January 2023. Issued by the IASB, it enhances financial transparency by standardizing how insurers recognize obligations. This transition accounting standard ensures consistency, improves comparability, and reduces variations in financial reporting across the industry.