Manufacturing overhead is essentially the hidden engine behind factory costs, covering all those indirect expenses like facility rent and utility bills. This is the critical connection that will bring your end product to your raw material.
These expenses are so hard to “see,” failing to keep an account of them will result in a huge hole in your budget. Underprice your products and have cash flowing out as fast as it comes in, such that the business ends up in financial ruin, is very easy without proper controls to track manufacturing overhead.
That is the reason you should keep an eye on your manufacturing overhead to make sure that you are making a profit. Any company that is accurate on this aspect will certainly have the right prices and consequently profit.
In this article, we will explain manufacturing overhead and walk you through the steps to accurately calculate it for your company.
Key Takeaways
Manufacturing overhead refers to all the indirect costs that a company faces during production. These costs are necessary for the manufacturing process but aren’t directly tied to any specific product.
Examples of manufacturing overhead include depreciation of machinery and buildings, utility costs, factory supplies, indirect labor expenses, and property taxes and insurance.
The importance of manufacturing overhead is to establish actual production costs, set competitive prices, provide choices in production methods, and improve cost management.
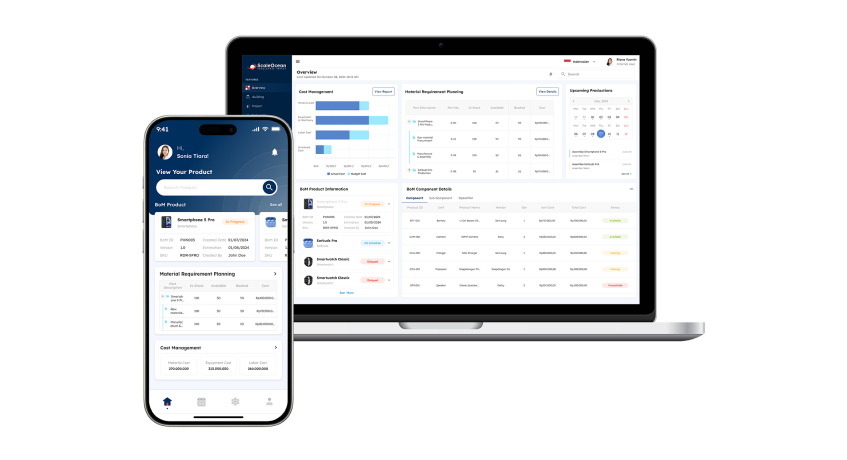
ScaleOcean manufacturing softwarecan automatically manage manufacturing costs, which can help businesses calculate and analyze the costs accurately and increase profitability by up to 50%.
Manufacturing overhead, also known as factory overhead, is all the indirect expenses that a company incurs when manufacturing its products. Such costs are needed during the manufacturing process but are not directly related to a particular product.
Examples of overhead costs are utilities, depreciation of factory equipment, and maintenance. Although these overhead costs in manufacturing are not directly attributed to the production of one item, they are necessary to ensure a smooth-running production process.
Wages to workers, such as supervisors and maintenance workers, are also included in overhead since these workers are not directly engaged in producing the product. This is then charged to all the units manufactured, and each product will contribute to the total cost.
Main Types of Manufacturing Overhead Cost
Overhead costs are the silent driving force behind every business operation, often overlooked but essential to smooth functioning.
There are several types of manufacturing overhead, such as fixed costs, variable costs, and semi-variable costs, that are essential for effective budgeting and cost control. Let’s examineeach category to uncover how they impact a business and why they matter, including:
Fixed Overheads: These are the fixed costs, such as rent and salaries, that do not change with the level of production. Although they provide a stable financial base upon which budgeting is based, it can cause financial strain during slow seasons.
Variable Overheads: These are costs that vary according to the level of production, i.e., raw materials and utilities. These are some of the things that businesses need to keep a close eye on because it is necessary to make sure that expenses remain in line with real factory production.
Semi-variable Overheads: These expenses have a fixed component and a variable component that varies with usage. The analysis of these assists firms to enhance their financial forecasting by comprehending complicated cost behaviors.
Applied Overhead: In this method, the cost of overhead is allocated to specific orders using the formula: Applied overhead = Estimated amount of overhead costs / Estimated activity of the base unit. It assists companies in precisely monitoring indirect production costs.
Key Components and Examples of Manufacturing Overhead
Manufacturing overheads have a set of indirect costs that are required to operate a factory but cannot be directly linked to particular products. These expenses guarantee the smooth running of the operations, such as expenses like utilities, insurance, and property taxes.
Knowing these overheads will assist businesses in making quality decisions regarding budgeting, allocation of resources, and pricing. The following are quick examples of manufacturing overhead that impact a company’s production costs:
Indirect Raw Materials: This includes things such as lubricants used in manufacturing that are not a part of the end product. They play a crucial role in ensuring the smooth running of the machines.
Indirect Labor: This includes support personnel such as supervisors and maintenance personnel. Although they do not construct the product, their labour is vital to the running of the factory.
Factory Costs and Supplies: These are the general costs, such as cleaning supplies or office supplies. They maintain the facility running, but are not attached to a particular product unit.
Depreciation on Machinery and Buildings: This is used to trace the loss of value of machinery and buildings with time. It assists companies in taking into consideration the wear and tear of their production assets.
Rent, Leasing, and Mortgage: These are the fixed costs of using the factory space or equipment. These payments are fixed overhead, whether it is a mortgage or a lease.
Maintenance and Repair Costs: To ensure that equipment is in excellent condition, regular replacement of parts and service. These expenses eliminate costly malfunctions and remedies.
Utilities Costs: This entails electricity, water, and gas that will be required to run the factory. Such bills are needed to ensure that the production lines are on the move.
Property Taxes and Insurance: Assets are secured by taxes on factory property and insurance premiums. These payments shield the business from major financial loss or damage.
Regulatory Costs: License fees and environmental permits will keep the factory legal. Adherence to these regulations is a compulsion for any contemporary manufacturing company.
Why is Manufacturing Overhead so Important?
The knowledge and proper calculation of manufacturing overhead costs are significant due to several reasons, as they aid businesses in gaining a clear image of the cost of production and enhance efficiency in business operations.
This can be simplified by using software such as Singapore manufacturing cost software, and this will allow the company to have better control of the cost. The following are the justifications as to why it is important to control overhead costs in the manufacturing process:
Profitability Analysis: You can use the knowledge of overhead to see the actual cost of each item produced. This makes sure that you are making good margins and the business is still profitable.
Tax Deductibility: Tax deductibility allows many indirect factory costs to be deductible to reduce your taxable income. Their correct tracking can lead to a decrease in the amount of taxes that the firm pays in general.
Cost Evaluation and Pricing: With the knowledge of your total overhead, you can work out the total cost of production. This information is essential in pricing in a manner that all the hidden costs are covered.
Setting Competitive Prices: Understanding the overhead costs will help you determine the right price in the market. You will be able to provide better deals to the customers and, at the same time, protect your bottom line.
Optimizing Production: Monitoring these costs will help identify the areas of resource wastage. It enables you to perfect your approaches and better manage your budget.
Financial Planning and Forecasting: With good overhead information, future budgeting becomes a lot more precise. It assists in estimating cash flow requirements and long-term planning of factory upgrades.
Adherence to GAAP Standards: Legal financial reporting will necessitate the proper allocation of overheads. Adhering to these guidelines will make sure that your records are transparent and well within the rules.
Analyzing Operational Efficiency: Monitoring indirect costs helps identify bottlenecks in the factory. It demonstrates what processes cost you too much and where you can enhance the production.
What Factors Affect Manufacturing Overhead?
Manufacturing overhead costs include indirect costs required to operate a production operation. These costs are useful in supporting industrial operations and establishing accurate prices, even though they are not directly related to the production of goods.
Here are the major components of manufacturing overhead costs:
Rent, leases, and mortgages: The cost of renting or owning a factory building is a significant overhead expense. For example, a business that rents warehouse space for storage or production will pay a monthly lease as part of its overhead.
Utility Costs: Electricity and water usage for the production facility, such as the power consumed by machines, lighting, and cooling systems.
Equipment Maintenance: Regular servicing of machines, like oil changes for factory equipment or calibrating machines to ensure efficiency and prevent breakdowns.
Asset Depreciation: The gradual reduction in value of machinery or factory buildings over time, which impacts costs for businesses. For example, a machine that depreciates $2,000 annually.
Workforce Expenses: Salaries for non-production workers such as supervisors, quality control, or maintenance staff who are essential for the factory’s operations but don’t directly make products. Also, these are considered key components of absorption costing, as they contribute to overall production costs.
Operational Supplies: Items like cleaning products, lubricants, or tools used in the daily operation of the factory, which support production without being part of the finished product.
Insurance Premiums: The cost of insuring the factory building, equipment, or workers against potential risks, such as fire or accidents, which are necessary for business protection.
Tax Obligations: Property taxes on the factory building or local taxes associated with operating the manufacturing business, which are often fixed annual costs.
Professional Fees: Costs for accounting, legal services, or consultation fees necessary to maintain compliance or optimize business operations.
How to Calculate Manufacturing Overhead?
Calculating these indirect costs is the only way to truly understand your production expenses and protect your margins. It turns vague estimates into hard data, allowing you to price your goods with absolute confidence.
To master your factory budget, follow these formulas and practical examples for accurate cost allocation:
Manufacturing Overhead Formula
To calculate the total manufacturing overhead, businesses must consider all indirect costs that go into production. These costs include things like utilities, factory maintenance, and employee wages not directly involved in production. The calculation involves two main formulas:
Manufacturing overhead = Total manufacturing overhead ÷ Total units produced
This first formula helps you determine the overhead cost per unit by dividing the total manufacturing overhead by the total number of units produced. This gives you a clear idea of how much overhead costs each product bears. Here is the second formula:
Manufacturing overhead = Fixed manufacturing overhead + Variable manufacturing overhead ÷ Number of units produced
This second formula breaks down the overhead costs into fixed and variable components. Fixed manufacturing overhead remains constant regardless of production levels, while variable overhead fluctuates based on the number of units produced.
Example of Manufacturing Overhead Calculation
Let’s assume that the total manufacturing overhead for your production process is $50,000, and you produced 5,000 units. Using the first Formula, you would divide the total overhead by the number of units produced to determine the overhead cost per unit. Here is the first formula:
Manufacturing overhead = $50,000 / 5,000 = $10 per unit
In this case, each unit would have a cost of $10 allocated for overhead, helping you better understand how much indirect costs are being assigned to each product. This gives a clear idea of production expenses.
Now, let’s break down the fixed and variable manufacturing overhead. Suppose your fixed manufacturing overhead is $30,000 and the variable manufacturing overhead is $20,000. Using the second formula, you would combine the fixed and variable costs and divide them by the number of units. Here is the second formula:
Manufacturing overhead = ($30,000 + $20,000) / 5,000 = $10 per unit
After applying the second formula, each unit still costs $10 in overhead. This example shows how breaking down overhead into fixed and variable components doesn’t change the cost per unit, but it does offer better insight into cost allocation.
What is Not Included in Manufacturing Overhead?
It is important to differentiate between costs that are associated with the factory and other costs of the business in order to report the correct financial statements. The knowledge of what to omit will help avoid the miscalculation of product costs and the overall profit margins.
The next list is of expenses that are strictly maintained as part of manufacturing overhead calculations:
Direct Costs: These are costs that are directly related to the production of a product, e.g., raw materials and direct labor. Since they can be traced to units, they are not included as overhead.
Non-Manufacturing Expenses: This group consists of expenses such as marketing, sales commissions, and administrative salaries. They are period costs that are associated with running the business and not the factory floor.
How Is Manufacturing Overhead Used?
Manufacturing overhead assists businesses in determining the total cost of production, which helps in proper reporting on finances, pricing decision-making, and operational control.
When these indirect costs of manufacturing are distributed across products, companies are then in a better position to determine whether their operations are really profitable. The use of manufacturing overhead is as follows:
Cost Allocation for Accurate Pricing
Cost Allocation to true Pricing is necessary as it would make the businesses know the actual cost of producing their products. The manufacturing overhead is allocated among the different products, and thus, all the indirect costs are incorporated in the final price computation.
Proper allocation of costs enables firms to set competitive and profitable prices. Unless overhead costs are properly allocated, products might be underpriced or overpriced, which can adversely affect profitability and long-term business success.
Financial Reporting and Compliance
Keeping a close eye on factory overhead is vital for both your tax filings and financial reports. To stay in line with official rules, every indirect cost must be tracked and documented with total precision.
Based on the statement we found from Lloyds Bank Trade notes, you must keep your accounting records for five years after the business year ends. This ensures your past transactions are always available for review or any necessary regulatory checks.
Clear overhead tracking also builds trust and helps leaders make smart choices while avoiding audit errors. This careful approach ensures that every single relevant cost is captured and reported accurately.
Budgeting and Cost Control
The manufacturing overhead analysis plays a critical role in ensuring that businesses can be able to reduce costs without affecting quality. Companies can identify potential savings opportunities by regularly evaluating their spending on such areas as utilities, equipment depreciation, and maintenance.
Good cost control measures enable manufacturers to maximize their budgets, enhance operational efficiency, and allocate resources in a prudent manner.
This will ensure profitability and, at the same time, ensure that the cost of production is kept in check, which will translate to a more sustainable business model.
Businesses can also properly assign overhead costs by learning how to analyze Cost of Goods Sold (COGS) so that proper financial reporting and manufacturing efficiency can be achieved.
Production Efficiency and Process Improvement
Manufacturing overhead is very important in deciding which factors are inefficient in production. A close examination of the overhead costs will allow businesses to identify the areas of waste or underutilized resources.
That will help to streamline the processes and improve the efficiency of the processes throughout the production cycle. As an illustration, high energy bills can be a pointer that the equipment is not performing efficiently.
This is an indicator that there needs to be an investment in more energy-efficient machinery, which will reduce the total cost over time and increase the overall production efficiency. These proactive measures can be used to achieve improved cost control and productivity gains.
Decision-Making in Manufacturing Strategy
The data on manufacturing overheads is central to the strategic decision-making in a company. Through cost analysis, businesses will be in a position to make informed decisions on the cost changes that need to be made, automation, or upgrading of the facilities to remain competitive.
This information aids companies in making decisions on whether to outsource production, invest in new technology, or optimize their workforce planning, which will be beneficial in the long-term growth.
Through manufacturing overhead information, organizations are able to make decisions that will see them continue to prosper in a continuously changing market.
The use of manufacturing overhead analysis in business operations will guarantee effective control of costs, strategic decision-making, and long-term success. Under ScaleOcean manufacturing software, businesses can easily monitor overhead costs, optimize resources, and enhance profitability.
How to Reduce Your Manufacturing Overhead
Singaporean firms should adopt smart ways to trim production overhead, which helps boost efficiency and margins. By removing waste and using resources better, you can effectively bring down your total manufacturing expenses.
Try these practical strategies to get started:
Optimize Manufacturing Workflow: Streamlining operations involves optimizing production workflows to eliminate bottlenecks and enhance efficiency. Several of the recommendations for manufacturing accounting software can support this by automating processes, cutting overhead, and improving overall product flow.
Implement Regular Preventive Maintenance: Staying ahead with routine upkeep prevents sudden breakdowns and pricey repairs. Checking gear early allows you to fix small issues fast, which saves both valuable time and company money.
Repurpose Components from Existing Equipment: Giving old machine parts a second life is a great way to save on new gear. Instead of tossing outdated components, see if they can be used elsewhere in your facility to keep costs down.
Employ an In-House Maintenance Specialist: Bringing a repair expert onto your team reduces the need for expensive outside contractors. Staff on-site can keep machines in peak shape with quick, hands-on care whenever it is needed.
Align Employees with Cost-Saving Objectives: Getting your team on board with savings goals helps build a more efficient culture. When people see the value in cutting waste, they often find clever new ways to help the business save.
Strengthen Partnerships with Suppliers: According to Investopedia, a survey by Ernst & Young of 200 senior supply chain executives found that 72% saw a deep negative impact from the pandemic, emphasizing that reliable partnerships can lead to better pricing and improved cash flow management.
Minimize Dependency on Office Supplies: Trimming your paper trail and moving to digital tools is a simple way to lower bills. Using electronic files boosts your speed while also supporting a much greener, more modern workplace.
Lease Out Unused Workspace: Renting out extra floor space creates a fresh income stream to help cover your overhead. Using every inch of your facility wisely improves your cash flow and makes your resource use more efficient.
Track and Manage Manufacturing Costs with ScaleOcean Software
Efficient cost management is crucial for manufacturers to maintain profitability and competitiveness. ScaleOcean Manufacturing Software streamlines cost tracking with an integrated, data-driven approach that connects production and financial metrics.
It provides real-time insights, ensuring every stage, from raw material procurement to final product costing, is closely monitored. This enables businesses to identify cost-saving opportunities, optimize production, and minimize inefficiencies to stay competitive.
Additionally, the software enhances forecasting and budgeting by leveraging accurate historical data and trends. ScaleOcean also offers free demos and consultations with team professionals for 100% optimal system implementation that suits your needs.
Features of ScaleOcean Manufacturing Software for Tracking Costs:
Real-time Cost Monitoring: Track labor, material, and overhead costs in real time, providing instant insights into cost structures.
Bill of Materials (BOM) Management: Link raw materials, components, and processes to calculate accurate manufacturing costs.
Cost Variance Analysis: Compare budgeted vs. actual costs to pinpoint areas for cost control.
Work Order Cost Tracking: Monitor the cost of individual work orders and batches to identify inefficiencies.
Integration with Financial Systems: Integrate seamlessly with accounting systems for a unified view of financials and cost reporting.
ScaleOcean manufacturing software provides manufacturers with real-time, accurate data throughout the production lifecycle, allowing for better decision-making to reduce costs and increase profitability. Its comprehensive cost management tools account for all expenses, including materials, labor, and overhead.
Seamless integration with other business systems improves visibility and communication, thereby increasing operational efficiency. Furthermore, the software provides valuable insights into cost variances, helping manufacturers refine processes and minimize waste.
Conclusion
Manufacturing overhead is necessary for estimating genuine production costs, although it is frequently underestimated. Managing indirect expenses such as rent, utilities, and maintenance leads to more precise pricing, better planning, and increased profitability.
Proper tracking helps companies in properly allocating resources, enhancing output, and improving financial planning, all while eliminating inefficiencies that undermine competitiveness. With the right tools, overhead management becomes more efficient.
ScaleOcean Manufacturing Software offers real-time cost tracking, variance analysis, and financial integration, providing clear visibility into expenses. These insights help businesses refine processes, reduce waste, and boost profitability.
Explore how ScaleOcean can support your manufacturing operations with a free demo and discover smarter ways to manage costs.
FAQ:
1. What are the 4 types of overhead?
Overhead costs are usually divided into four key types, which are production overhead, administrative overhead, selling overhead, and financial overhead. These types represent various indirect costs, which can include fixed, variable, or semi-variable costs.
2. Is manufacturing overhead an asset or expense?
Manufacturing overhead is considered an expense and is included in the cost of goods sold (COGS). It accounts for indirect production costs and is allocated to work-in-process (WIP) and finished goods inventory during production.
3. What does 40% overhead mean?
For instance, if your overhead costs amount to $70,000 and direct labor costs are $175,000, the overhead rate is 40%. This indicates that for every dollar spent on direct labor, you are spending 40 cents on overhead costs.
4. How do I choose the right overhead allocation method?



 Key Takeaways