


Periodic inventory system is an accounting method that tracks inventory and calculates the cost of goods sold (COGS) through occasional physical counts at set intervals, such as monthly, quarterly, or yearly rather after every transaction.
However, for Philippine businesses, there are several factors that should be taken into consideration when choosing the right inventory method. This article will help you to optimize warehouse productivity by using a periodic inventory system.
 Key Takeaways
A periodic inventory system is an inventory accounting method where a business does not continuously update its inventory account whenever goods are purchased or sold.
Instead, purchases are recorded separately during the accounting period, while the actual inventory balance is determined through a physical count at the end of the period.
Under this method, the business determines its ending inventory through a physical stock count. The ending inventory is then used together with beginning inventory and purchases to calculate the cost of goods sold (COGS). The basic formula is:
Cost of Goods Sold = Beginning Inventory + Net Purchases – Ending Inventory
A periodic system is generally easier to maintain than a highly detailed real-time inventory system. Businesses with fast-moving products may therefore need additional stock audits or manual checks to identify discrepancies.
The periodic inventory process records purchases throughout the accounting period and supports inventory control by determining remaining stock through physical counting at specific intervals. The process generally involves the following steps:
For the business, the inventory value at the beginning of the accounting period is the value carried over from the previous accounting period. For instance, if the inventory at the beginning of the accounting period is ₱75,000, this will denote the amount of inventory available at the start of the accounting period.
It does not directly record the purchase of inventory in the Inventory account, rather it records it in a Purchases account. For example, if ₱50,000 is bought, it will be recorded in the books as debit Purchases, ₱50,000 and credit Accounts Payable/Cash, ₱50,000.
At the end of the accounting period, products left in the store, warehouse or other inventory areas are counted. If a business has multiple stores, each store should be listed and the numbers matched to the ones the business has on-hand.
Once the inventory has been completed, the company estimates the monetary value of the remaining inventory. This amount is for COGS which are still available for sale and have not yet been recognized as COGS.
For example, with ₱75,000 beginning inventory, ₱50,000 in net purchases, and ₱45,000 ending inventory, the COGS would be calculated as: ₱75,000 + ₱50,000 – ₱45,000 = ₱80,000.
The resulting COGS is used when preparing financial statements and evaluating business profitability. Since inventory is only updated periodically, businesses need reliable counting procedures to minimize discrepancies.
Moreover, maintaining accurate inventory tracking between physical counts can also help businesses monitor stock movements, identify discrepancies earlier, and make better purchasing decisions.
A periodic inventory method may be suitable for companies that have a fairly straightforward inventory system, particularly for small retailers, wholesalers, and startups. It has several primary benefits, such as:
It is important to know the difference between periodic inventory and perpetual inventory systems when determining the monitoring and recording of inventory. The difference is that inventory records are updated more or less often, below are the differences:
| Factor | Periodic Inventory System | Perpetual Inventory System |
|---|---|---|
| Inventory Updates | At specific intervals. | Continuously. |
| Physical Counting | Required to determine ending inventory. | Used mainly for verification. |
| Purchase Recording | Usually recorded in Purchases. | Usually recorded directly in Inventory. |
| COGS Calculation | Determined at the end of the period. | Updated with each sale. |
| Real-time Stock Visibility | Limited. | High. |
| Technology Requirement | Generally lower. | Generally higher. |
| Best Suited For | Smaller or low-volume operations. | High-volume or complex operations. |
For example, imagine a sari-sari store that sells a relatively small selection of products. The owner may periodically count remaining products and compare them with purchase and sales records.
Meanwhile, a large retailer operating several branches in Metro Manila may need continuous visibility into stock levels. With thousands of transactions daily, waiting until the end of the month to determine inventory levels could make it difficult to identify.
A perpetual inventory method can provide more immediate information because each purchase, sale, or adjustment can update the records. However, that does not mean a perpetual system is better, the appropriate choice depends on business requirements.
A periodic inventory system is generally suitable for businesses with simple inventory operations that do not require real-time stock information. Consider using this method when:
 Also Read: What is Inventory Valuation? Importance & Methods
Let’s take a quick look at an example of a small retail company and use the Philippine peso amounts. A small hardware store has ₱150,000 worth of inventory at the beginning of a month, buys more stock for ₱80,000 worth, and at the end of the month has a physical stock count of ₱120,000 worth of inventory.
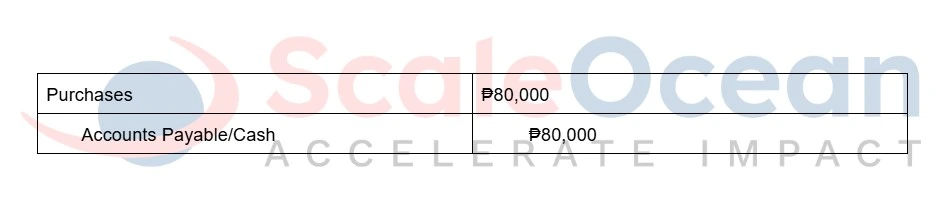
Note down purchases made in the time frame:
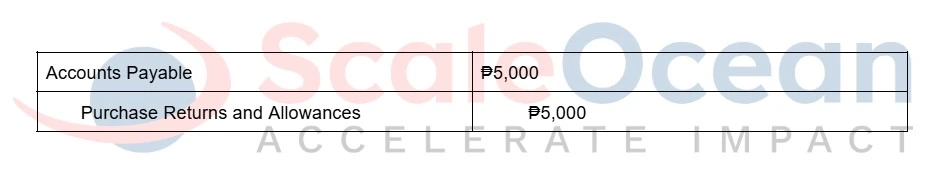
If purchase returns (such as return of defective items valued at ₱5,000) are made to a supplier:
At period-end, closing entries to compute COGS:
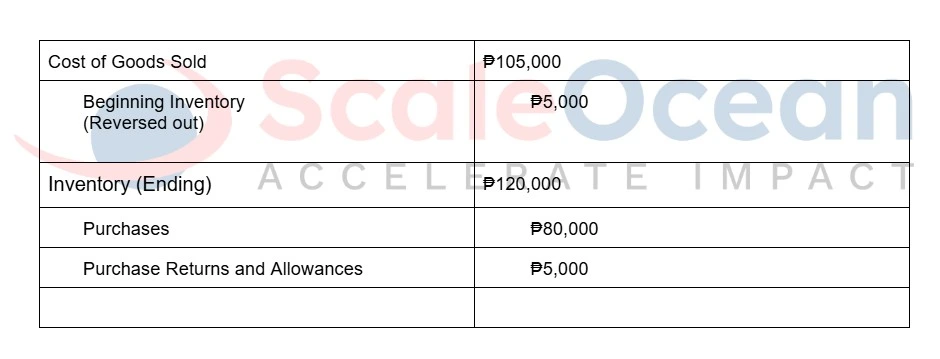
Using the formula:
Beginning Inventory + Net Purchases – Ending Inventory = Cost of Goods Sold
Therefore, the calculation is ₱150,000 + ₱75,000 – ₱120,000 = ₱105,000
The result of this COGS is then incorporated in the income statement and the ₱120,000 inventory is the beginning inventory for the next accounting period.
A periodic inventory system can use different inventory valuation methods to determine the value of ending inventory and calculate COGS. The most commonly discussed methods include FIFO, LIFO, and Weighted Average Cost (WAC).
However, businesses in the Philippines should note that under IAS 2, which forms part of the Philippine financial reporting framework, FIFO and WAC are permitted for ordinarily interchangeable inventory, while LIFO is not permitted.
To see how each method affects inventory valuation, consider a Philippine retailer with the following inventory purchases:
FIFO assumes that the inventory purchased first is sold first. Therefore, the 180 units sold would consist of the 100 units purchased at ₱100 and 80 units purchased at ₱120.
The COGS would be:
(100 × ₱100) + (80 × ₱120) = ₱19,600
The remaining 120 units would consist of:
20 units × ₱120 = ₱2,400
100 units × ₱140 = ₱14,000
Therefore:
Ending Inventory = ₱16,400
For Philippine businesses, FIFO can be useful when the actual movement of goods generally follows the order in which inventory is purchased, such as products with expiration dates or items that need to be rotated regularly.
LIFO assumes that the most recently purchased inventory is sold first. Using the same example, the 180 units sold would consist of 100 units at ₱140 and 80 units at ₱120. The COGS would be:
(100 × ₱140) + (80 × ₱120) = ₱23,600
The remaining 120 units would consist of:
20 units × ₱120 = ₱2,400
100 units × ₱100 = ₱10,000
Therefore:
Ending Inventory = ₱12,400
However, LIFO is included here for educational comparison only. It is not permitted under IAS 2 for financial reporting, so Philippine businesses reporting under PFRS should not use LIFO to measure ordinarily interchangeable inventory.
The Weighted Average Cost method calculates an average cost for all units available during the accounting period. This spreads the total inventory cost across the units available for sale. First, calculate the total inventory cost:
(100 × ₱100) + (100 × ₱120) + (100 × ₱140) = ₱36,000
There are 300 units available, so the weighted average cost per unit is:
₱36,000 ÷ 300 = ₱120 per unit
With 180 units sold:
COGS = 180 × ₱120 = ₱21,600
The remaining 120 units are valued at:
Ending Inventory = 120 × ₱120 = ₱14,400
WAC can be practical for businesses selling large quantities of similar or interchangeable products because it reduces the impact of fluctuations between individual purchase prices. IAS 2 permits the weighted average cost formula for ordinarily interchangeable inventory.
Using the same underlying inventory data, each inventory valuation method such as FIFO, LIFO, and Weighted Average produces distinct Cost of Goods Sold (COGS) and ending inventory values. Below here are the comparison:
| Method | COGS | Ending Inventory |
|---|---|---|
| FIFO | ₱19,600 | ₱16,400 |
| LIFO | ₱23,600 | ₱12,400 |
| WAC | ₱21,600 | ₱14,400 |
These differences show why selecting an appropriate inventory valuation method matters. The method used affects COGS, ending inventory, gross profit, and reported financial results. In here, LIFO is shown for educational comparison and is not permitted under IAS 2/PFRS for financial reporting.
Therefore, for Philippine businesses, the selected method should also be applied consistently and in accordance with the applicable financial reporting requirements to gain better performance of inventory management.
Many Philippine MSMEs, particularly those at their initial stage or with a small product line, still use the periodic inventory system, which is practical and economical for them.
However, its greatest virtue, simplicity, is also its disadvantage. Further, without real-time tracking, businesses may have limited visibility into their actual stock levels and COGS until the end of each accounting period.
As transaction volumes increase or your business expands to multiple branches, combining smart technology with physical verification becomes essential. Therefore, this helps to keep track of the stock and will help in managing the warehouse.
If you’re looking to optimize periodic stock counts, you should explore the inventory module of ScaleOcean Atlas. It can enhance the efficiency of business warehouse activities with its warehouse management supported with ScaleMind AI automation.
Schedule of consultation of ScaleOcean Atlas to see how a more integrated warehouse management approach can support your business operations.
A periodic system relies on periodic physical inventories, and a perpetual system keeps a running record of stock changes. Periodic inventory is easier, but doesn’t offer real-time visibility.
Use this formula: Beginning Inventory + Purchases – Ending Inventory = COGS. The ending inventory is based upon a physical inventory taken at the end of the accounting period.
Establish inventory records and schedule physical counts, determine valuation method, accurately record purchases and sales, complete COGS calculations and make inventory adjustments at the end of the period.