


Inventory valuation of warehouse management is an aspect of accounting that helps to assess the monetary worth of products that a company keeps. This type of valuation can be beneficial for small or large businesses across all industries.
Correct inventory valuation is crucial for any company in the Philippines to monitor the cost of goods, enhance profit, and make informed buying decisions. Learn how to maximize the use of your space and value for warehouse optimization here.
 Key Takeaways
Inventory valuation is a way to determine the monetary worth of unsold inventory at the end of an accounting period. The value encompasses goods that are sold and bought for resale, raw material, work in process (WIP), or finished product.
Inventory is considered one of the largest current assets for many businesses. Because of this, its value directly affects Cost of Goods Sold (COGS), gross profit, net income, and balance sheet sheet accuracy.
For instance, a distributor in the Philippines that buys the products at varying prices during the year may not just guess the value of the leftover stock. Rather, the company has to use a generally accepted valuation principle, such as FIFO or LIFO, to calculate the ending inventory value.
In the Philippines, inventory accounting follows PAS 2 (Inventories), part of the Philippine Financial Reporting Standards (PFRS), which mirrors international IFRS rules. PAS 2 requires that inventory be valued at whichever is lower, cost or net realizable value (NRV), and that the same costing method be used consistently for similar types of inventory.
Inventory valuation is a significant aspect of a business’s ability to know the actual value of its inventory. Several reasons why inventory valuation is important in maintaining a consistent warehouse management are mentioned below:
Although the final inventory value depends on the costing method used, the basic inventory valuation formula starts with determining the total cost of inventory available during the accounting period.
Ending Inventory = Beginning Inventory + Purchases – Cost of Goods Sold (COGS)
This formula is used to determine the physical flow of stock, below are the formulas used to calculate inventory value in warehouse management:
The ending inventory figure, the value of what’s left unsold, is what gets reported on the balance sheet. To arrive at that number, businesses need two things: the quantity of stock on hand, usually confirmed through a physical count, and the unit cost assigned to each item, which depends on the valuation method used.
Valuation of inventory is an important aspect of financial reporting, particularly for expanding businesses. When there are a number of warehouses, or the value of inventory items can vary, it can be difficult to determine the value of inventory.
Companies tend to have thousands of Stock Keeping Units (SKUs) within various products, in several warehouses. The value of inventory changes whenever there is a purchase, sale, return, stock transfer or adjustment to inventory.
For businesses that rely on periodic inventory methods, keeping track of these changes can be even more challenging because inventory quantities and values are typically determined at specific intervals rather than updated continuously.
In contrast, the perpetual inventory method continuously updates inventory records as transactions occur, making it easier to monitor changes in stock quantities and values.
Further, to overcome these problems, many companies implement software that automates inventory control by tracking movements and updating stock values on the spot
In the Philippines, there are numerous businesses that are importing raw materials or finished goods from overseas suppliers. International sourcing offers competitive pricing and a larger product selection, but can be more complex when it comes to inventory valuation.
Imported inventory may also come with extra fees like freight charges, import taxes, and currency exchange rate fluctuations. Additionally, a centralized system is needed to enhance warehouse valuation to bring together purchasing information.
Getting inventory valuation wrong doesn’t just distort a balance sheet, it throws off the cost of goods sold, understates or inflates gross profit, and can trigger discrepancies during a BIR audit.
Accurate valuation also becomes easier when businesses have a structured approach to managing warehouse inventory, especially when tracking stock across multiple locations.
In the case of Philippine SMEs operating on multiple SKUs across various warehouses, selecting the right inventory valuation formula will impact the accuracy of their books. These are the most common formulas that used in management:
First-In, First-Out (FIFO) assumes that the oldest stock is the first to be sold. The cost of goods sold reflects the cost of the oldest purchases, and ending inventory reflects the most recently purchased prices.
Formula:
In periods of rising prices, common with imported raw materials subject to peso depreciation, FIFO produces a lower COGS and a higher reported gross profit, since older, cheaper stock is expensed first.
Secondly, LIFO assumes the most recently purchased inventory is sold first. Cost of goods sold is calculated using the cost of the newest units, while ending inventory reflects the cost of the oldest, unsold stock.
Formula:
In periods of rising prices, LIFO produces a higher COGS and lower reported gross profit, since the most expensive (recent) stock is expensed first, which also lowers taxable income under systems that allow it, such as US GAAP.
It’s worth noting that LIFO isn’t permitted under PAS 2 (the Philippine equivalent of IAS 2), so it can’t be used for statutory financial reporting or BIR-compliant books locally, to solve this businesses here typically default to FIFO or weighted average.
This method recalculates the average cost of all units available for sale each time a new purchase is made, then applies that single average cost to both COGS and ending inventory.
Formula:
This smooths out price fluctuations, which makes it a practical choice for businesses dealing with volatile input costs, such as construction materials or fuel-dependent logistics operations.
Beyond choosing a costing method, Philippine businesses must report inventory at whichever amount is lower: what they originally paid for it (cost), or what they can actually still sell it for (net realizable value, or NRV).
As a result, this Lower of Cost or Net Realizable Value (LCNRV) rule doesn’t allow businesses to overstate the value of stock that has become damaged, obsolete, or just less selling than it was when it was purchased.
For instance, if there has been a drop in the market value of the retailer’s electronic gadgets as newer models have come up to market, inventory should be written down to the lower realizable value, not original cost.
 Also Read: What is Inventory Tracking? A Guide for Filipino Businesses
Let’s examine the following example of a retail company in the Philippines. This example helps you understand the impact of different inventory valuation approaches on COGS, inventory value and financial statements.
The firm has to buy the same product multiple times for the month at varying prices because of fluctuations in supplier costs. The business must know what to report as the value of its remaining inventory at the end of the month in order to prepare its financial statements.
| Transaction | Units | Unit Cost | Total Cost |
|---|---|---|---|
| Beginning Inventory | 100 | ₱100 | ₱10,000 |
| Purchase 1 | 200 | ₱110 | ₱22,000 |
| Purchase 2 | 150 | ₱120 | ₱18,000 |
| Total Goods Available for Sale | 450 | – | ₱50,000 |
During the month, the company sells 300 units, leaving 150 units in ending inventory. Here’s the example of the calculations using several methods to have better understanding of the practices:
Calculation:
100 units × ₱100 = ₱10,000
200 units × ₱110 = ₱22,000
Cost of Goods Sold (COGS): ₱32,000
The remaining inventory consists of: 150 units × ₱120 = ₱18,000
Ending Inventory (FIFO): ₱18,000
Weighted Average Cost = Total Cost ÷ Total Units
= ₱50,000 ÷ 450 = ₱111.11 per unit
Then calculate ending inventory: 150 units × ₱111.11 = ₱16,666.50
Ending Inventory (WAC): ₱16,666.50
| Method | Ending Inventory | Cost of Goods Sold |
|---|---|---|
| FIFO | ₱18,000 | ₱32,000 |
| Weighted Average Cost | ₱16,666.50 | ₱33,333.50 |
This example shows that different inventory valuation methods produce different inventory values and Cost of Goods Sold, even though the same number of products is purchased and sold.
During periods of rising prices, FIFO generally reports a higher ending inventory value, while Weighted Average Cost provides a more balanced valuation by averaging inventory costs.
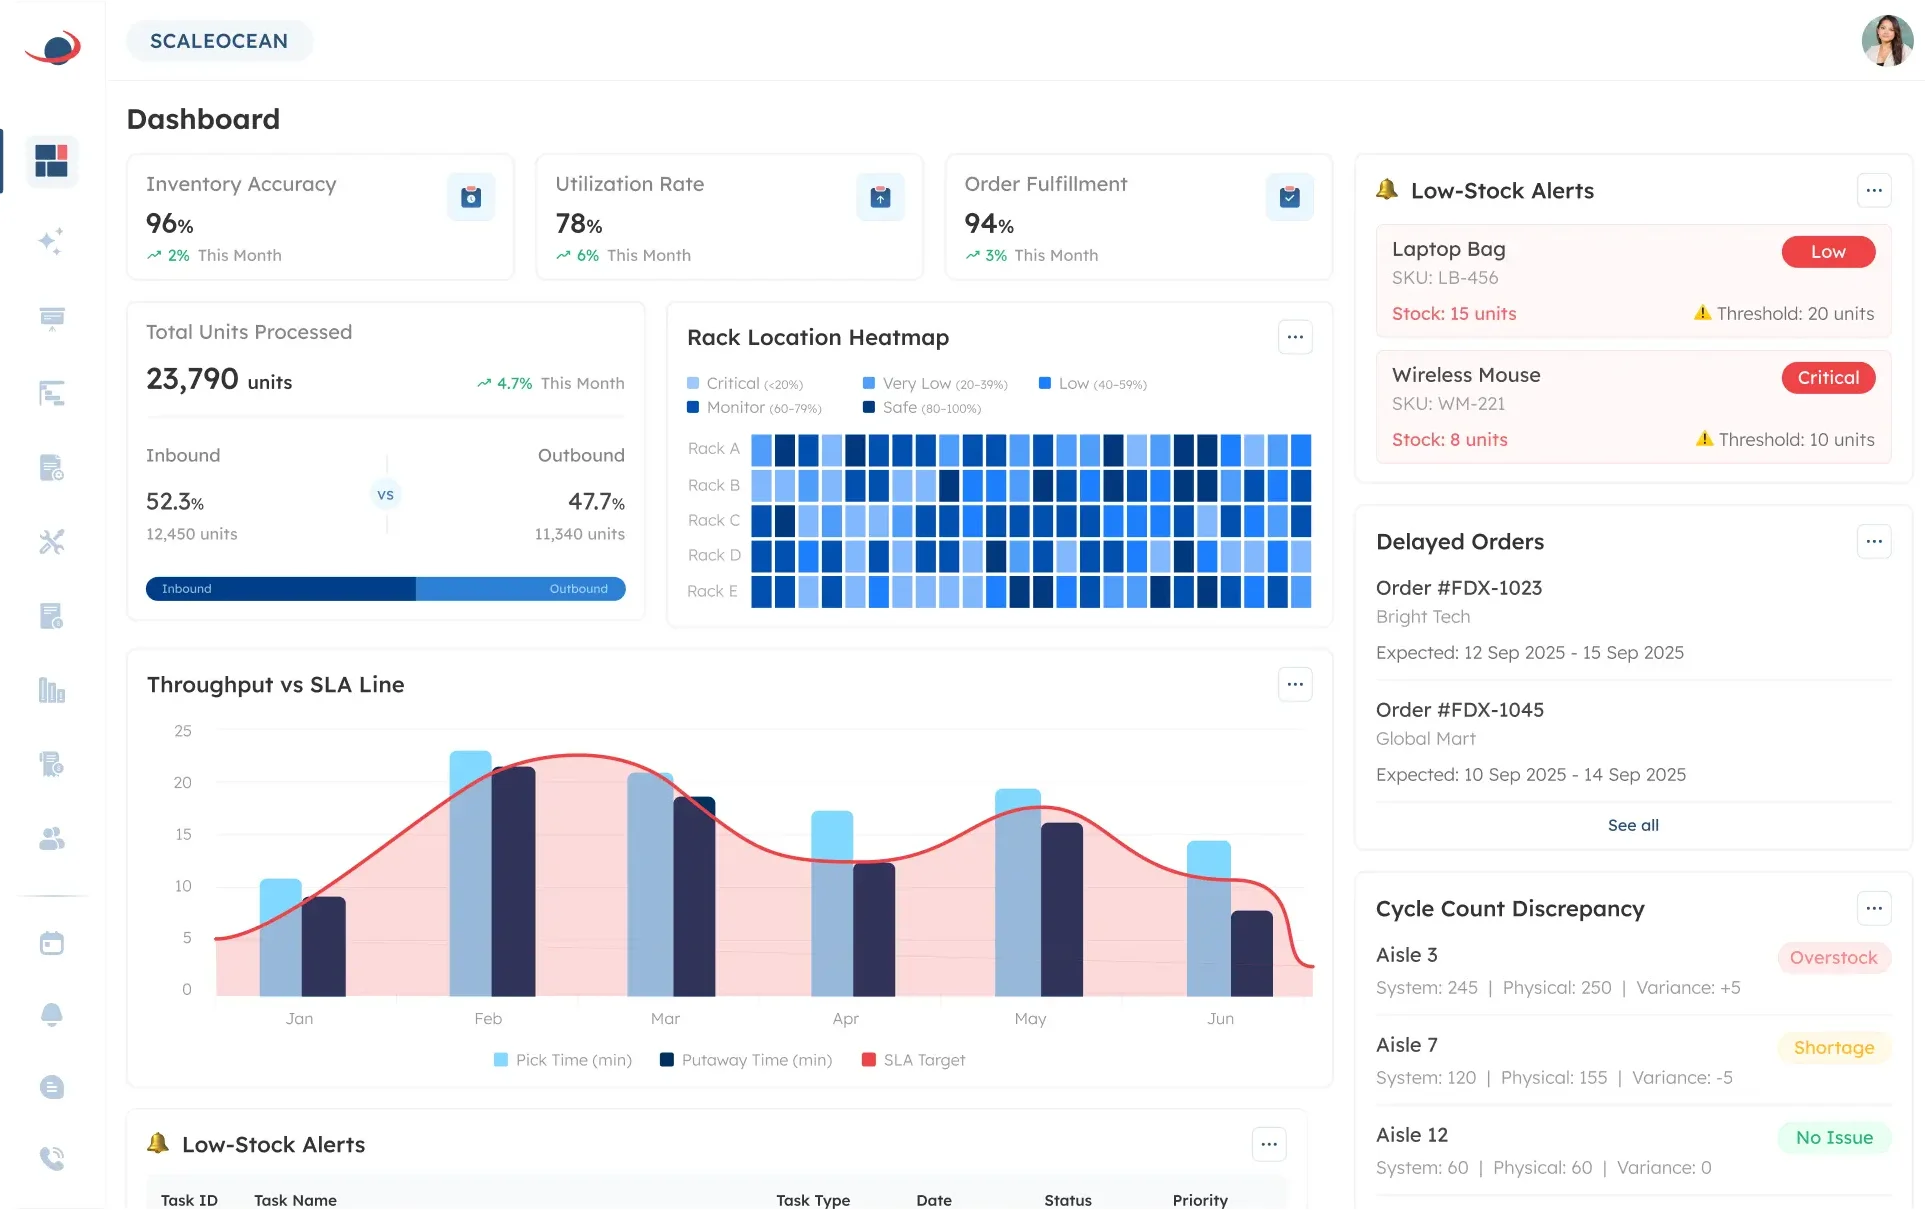
As inventory increases, manually calculating inventory valuation can become increasingly complex. It is difficult to accurately value inventory for businesses that have several warehouses, frequent inventory changes, and fluctuating purchase costs.
Inventory Module of ScaleOcean Atlas helps businesses transform inventory valuation from a periodic task into an automated, real-time process. Every inventory transaction, from purchasing and receiving goods to sales, returns, and stock transfers.
Beyond inventory tracking, ScaleOcean Atlas is equipped with ScaleMind, an AI-powered assistant that analyzes inventory trends, identifies unusual stock movements, and provides actionable recommendations for inventory planning.
Schedule consultation to see how ScaleOcean Atlas can simplify inventory valuation while improving inventory visibility and financial accuracy. The features include:
Accounting for inventory is a vital process when it comes to determining the monetary worth of inventory and providing correct financial reporting. Knowing the right inventory accounting principles will help businesses determine the cost of goods sold.
As businesses in the Philippines continue to expand, managing inventory valuation manually can be more complex. An integrated inventory management system ensures a more automated tracking and integrates the warehouse with the accounting system.
If you’re looking for a smarter way to simplify inventory valuation, ScaleOcean Atlas provides a warehouse management solution that integrates inventory, procurement, sales, and accounting in a single platform.
Book a consultation with ScaleOcean Atlas today to learn how it can assist your business to streamline inventory valuation, strengthen financial reporting, and optimize warehouse operations as your business expands.
Select an inventory valuation method (FIFO, LIFO, Weighted Average Cost) and use it for your inventory records. If necessary, compare with the net realizable value (NRV) and report the lesser amount.
The primary inventory valuation techniques are: FIFO (First In, First Out), LIFO (Last In, First Out), Weighted Average Cost (WAC), Specific Identification, and the Retail Inventory Method. There are different values on inventory that each approach puts on it.
Simple average method is a method of computing the cost of inventory by accumulating the various purchase prices and dividing the sum by the number of purchase prices. It is not based on the quantity bought at each price as is the Weighted Average Cost.