Net take home pay or usually referred to as take home pay is the amount of money you actually receive after taxes, mandatory government contributions, and other applicable deductions are subtracted from your salary.
Managing payroll can be complex due to numerous details and compliance requirements. Because HR teams handle salary calculations every month, they must carefully navigate regulations and tax deductions. Here is an overview of the process and how to enhance its accuracy.
Key Takeaways
Net take-home pay is the actual salary received after taxes, required government deductions and other approved fees have been taken out.
Gross pay is the amount of money earned before any deductions are made, and net pay is the money you can use to pay bills and other expenses.
Philippine net take-home deductions include SSS (up to ₱1,750) and PhilHealth (2.5%), Pag-IBIG (capped at ₱200) and BIR tax for income above ₱250k.
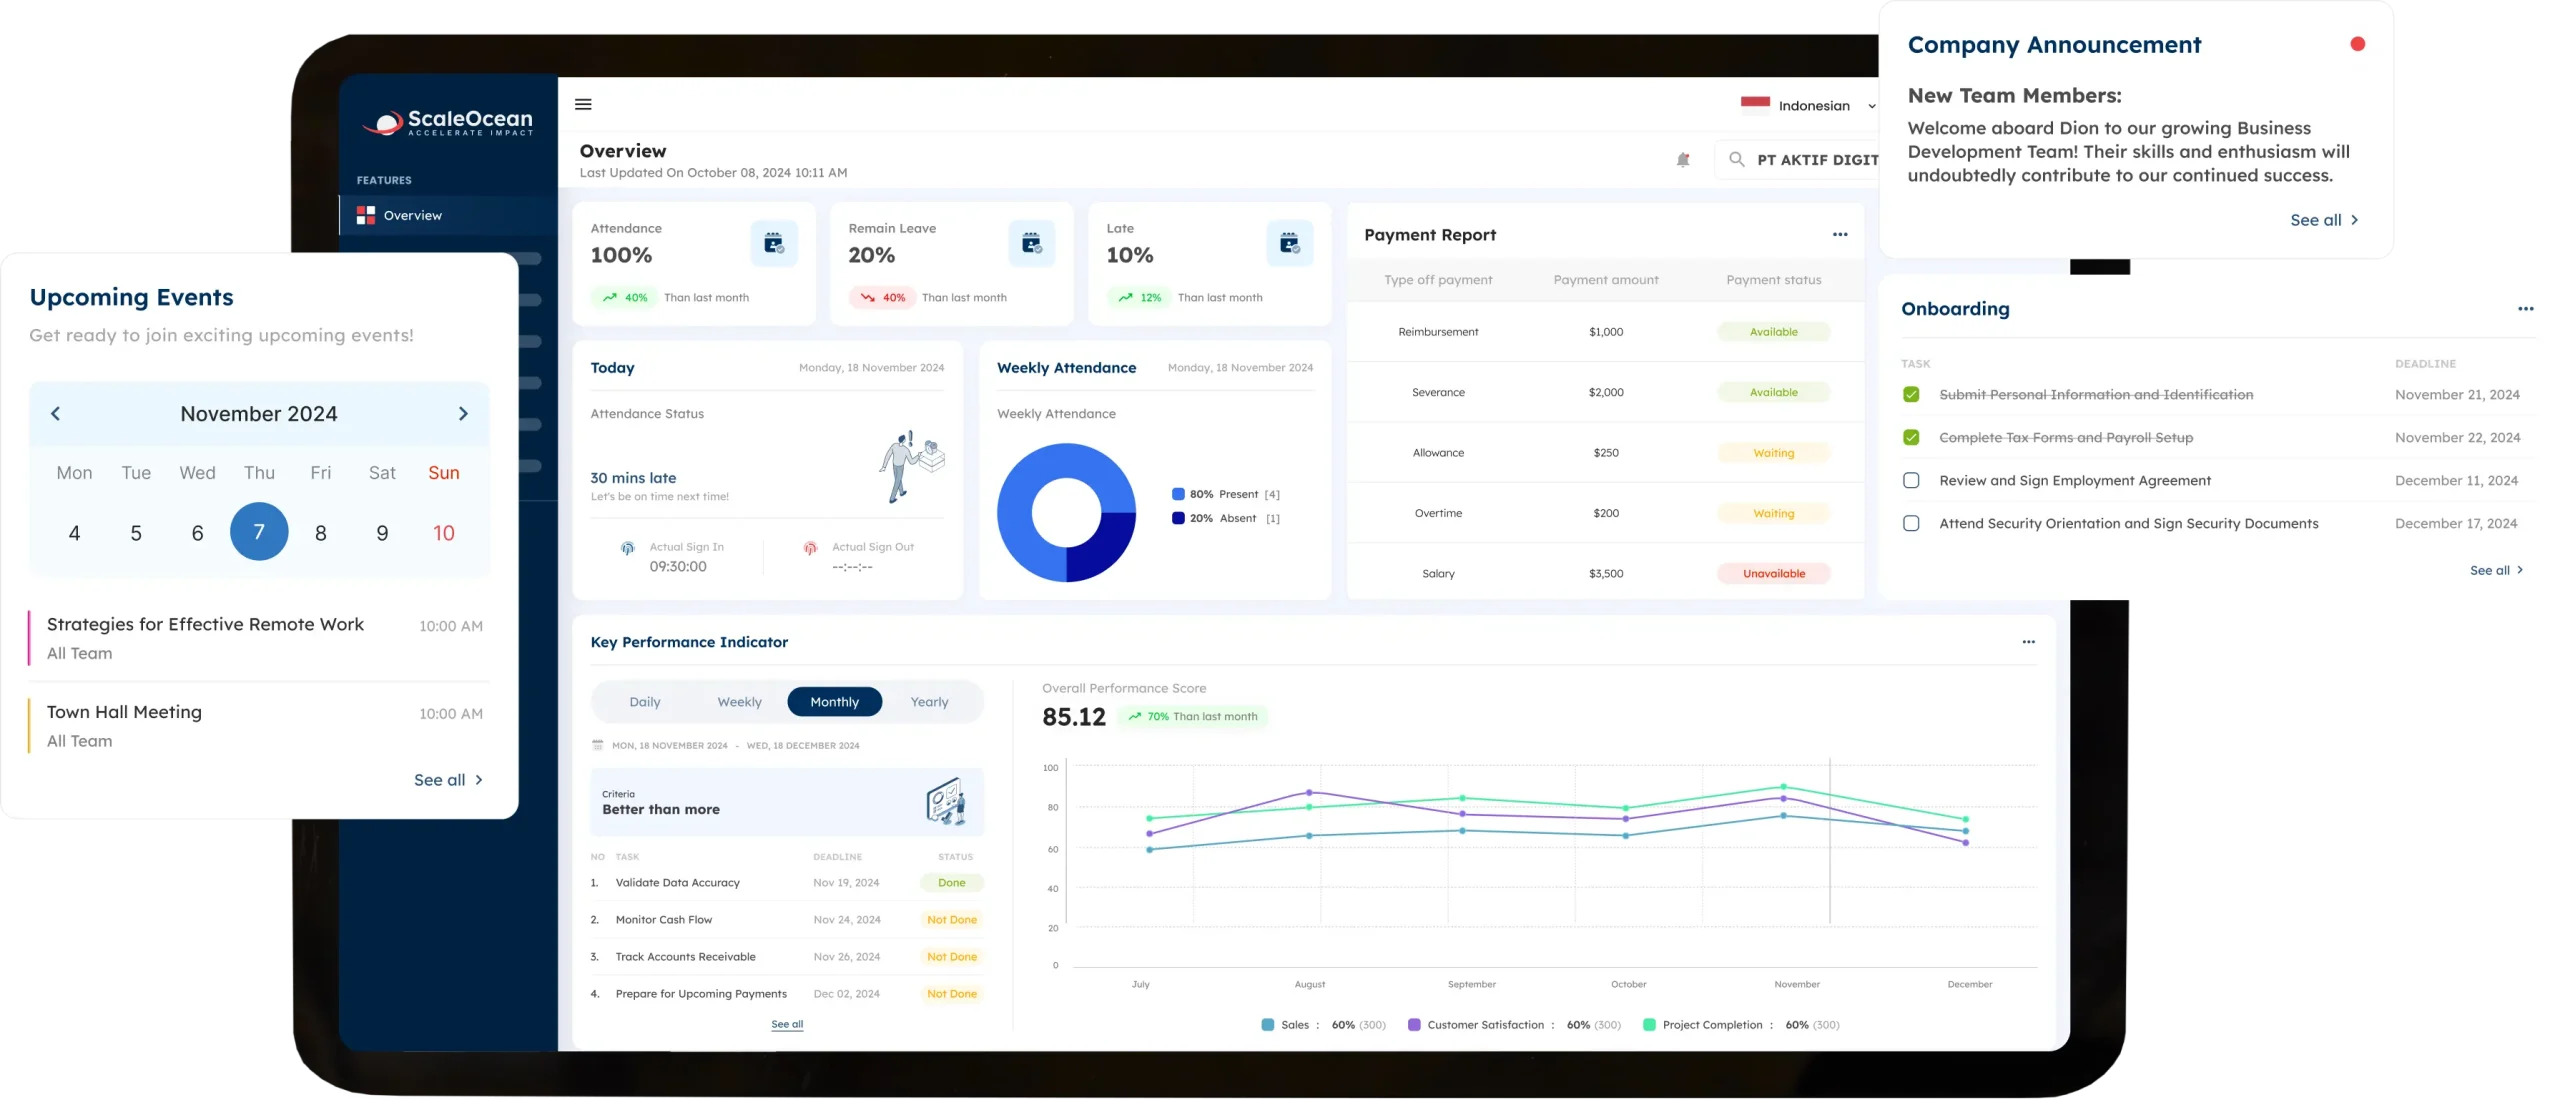
ScaleOcean Atlas streamlines payroll, attendance, and tax deductions by automating manual tasks with the power of ScaleMind AI, reducing errors and overall HR workload.
Net pay is the amount that an employee receives after all deductions have been taken from the gross pay. It is also known as take home pay because it is the money that an individual has for living expenses, savings, debt payments and their personal needs.
For instance, a worker getting paid the salary of ₱35,000 per month may not be given the entire amount in his bank account. Their employer might withhold SSS, Pag-IBIG and PhilHealth contributions and withhold income tax before giving them the remaining balance.
So, what determines take home pay? Net pay is based on an employee’s compensation, contribution rates, tax status and payroll structure. In some cases, an employee’s take home pay could vary based on the same gross salary.
It is also helpful for employers to understand the difference between the gross and net pay. Payroll becomes more easily understood and verifiable when employees can see how gross earnings relate to their pay.
2. Differences Between Net Pay and Gross Pay
While gross and net pay are both significant in examining compensation, they refer to different points in the payroll process. Gross pay refers to the salary or wages before deductions and net pay refers to the salary or wages after applicable deductions. Here are the differences:
Aspect
Gross Pay
Net Pay
Meaning
Total earnings before deductions
Earnings after applicable deductions
Includes
Basic salary, overtime, commissions, and applicable allowances or bonuses
The remaining amount after deductions
Government Contributions
Not yet deducted from gross earnings
Employee contributions are deducted
Income Tax
Not yet deducted
Applicable withholding tax is deducted
Main Purpose
Evaluating salary packages and total earnings
Budgeting and determining actual pay received
The Net Take Home Pay Formula
The basic formula for calculating net take home pay is:
Net Pay = Gross Pay – Total Deductions
For a more detailed calculation in Philippines, here is the formula:
Net Pay = Gross Salary – (SSS + PhilHealth + Pag-IBIG + BIR Withholding Tax)
Deduct Mandatory Contributions:
SSS (Social Security System): You pay 5% of your salary bracket. The lowest bracket is ₱5,000 and the highest is ₱35,000, so you pay between ₱250 and ₱1,750 a month. If you earn around ₱35,000 or more, you pay the maximum of ₱1,750. Government employees pay into GSIS instead, at 9%.
PhilHealth: The total premium is 5% of your monthly basic salary, and you and your employer each pay half (2.5% each). Salaries below ₱10,000 are treated as ₱10,000, and salaries above ₱100,000 are treated as ₱100,000. So your share is between ₱250 and ₱2,500 a month.
Pag-IBIG (HDMF): You pay 2% of your monthly pay, or 1% if you earn ₱1,500 or less. Only the first ₱10,000 of your pay counts, so the most you pay is ₱200 a month.
3. The Components That Are Deducted from Gross Pay
There are some deductions that may impact an employee’s take home salary in the Philippines. Some are mandated by law and others are based on the employee’s situation, benefits, or permitted payment options.
a. Social Security System (SSS) Contributions
The SSS must be able to offer social protection benefits such as benefits on retirement, sickness, maternity, disability and death benefits. Employed private-sector workers usually make contributions via payroll deductions, with employers making the same contribution.
As of January 1, 2025, the SSS contribution is 15% of the Monthly Salary Credit (MSC), split as 10% employer and 5% employee. The MSC ceiling is ₱35,000, so the employee’s maximum monthly pay is ₱1,750.
b. PhilHealth Premium Contributions
PhilHealth contributions are used to finance the national health insurance program of the country. Employed direct contributors premium is paid half by the employer and half by the contributor and is deducted from the payroll.
The premium is 5% of Monthly Basic Salary: 2.5% employer and 2.5% employee. It uses a ₱10,000 floor and ₱100,000 ceiling, so the employee’s monthly share ranges from ₱250 to ₱2,500.
c. Pag-IBIG Fund Contributions
The Pag-IBIG Fund is the Home Development Mutual Fund which provides savings and housing benefits. The contributions are made by employees and employers according to the rules of membership and the limit of compensation.
Employees earning over ₱1,500 monthly contribute 2%, matched by a 2% employer share. Under Pag-IBIG Fund Circular No. 460, the Maximum Fund Salary is ₱10,000, capping the employee’s mandatory contribution at ₱200 per month. The employer likewise contributes ₱200, for a total monthly contribution of ₱400.
d. Withholding Income Tax
Under the rules of the BIR, employers normally deduct income tax from income from employment. The amount varies based on taxable income, payroll period, and taxable/incompatible compensation and deductions.
As per the income tax schedule which has been in effect since January 1, 2023 under Republic Act No. 10963 or also known as the TRAIN Law, income tax rates of 0% apply on income earnings of up to ₱250,000 annually. The higher one’s income, the higher the tax, and the threshold is applied to taxable compensation, not gross salary.
Unlike many countries that follow a strict earnings-to-tax-rate model, the income tax in the Philippines is progressive and calculated based on the excess that remains in each set upon earning bracket. Said earning brackets are divided as such:
Annual Taxable Income (PHP)
Tax Computation / Rate
₱250,000 and below
0% (Exempt)
Over ₱250,000 to ₱400,000
15% of the excess over ₱250,000
Over ₱400,000 to ₱800,000
₱22,500 + 20% of the excess over ₱400,000
Over ₱800,000 to ₱2,000,000
₱102,500 + 25% of the excess over ₱800,000
Over ₱2,000,000 to ₱8,000,000
₱402,500 + 30% of the excess over ₱2,000,000
Over ₱8,000,000
₱2,202,500 + 35% of the excess over ₱8,000,000
e. Other Applicable Deductions
In addition to the compulsory contributions and taxes, other deductions can affect the amount of pay that is received, depending on the employee’s circumstances. Below here are the examples include:
Pag-IBIG or other loan repayments: Scheduled amortizations deducted through payroll.
Salary advances: Reimbursements for an advance provided by the employer, as per rules.
Insurance or benefit premiums: Employee contributions to insurance or benefit premiums that are optional or provided by the employer.
Other authorized deductions: Additional deductions that are lawful and properly authorized.
Not every employee will have these deductions. Employers should distinguish mandatory contributions from optional deductions and ensure that every deduction is correctly documented.
4. How to Calculate Net Pay in the Philippines?
To understand how to calculate net pay, start with the employee’s total earnings for the relevant payroll period. Here is a practical step-by-step approach for Philippine employees and payroll teams:
Step 1: Calculate gross income. Include the employee’s basic salary, overtime pay, commissions, bonuses and allowances for the payroll period. Determine if each item is taxable.
Step 2: Calculate the SSS contribution. Use the current SSS contribution schedule to determine the employee’s share based on the applicable Monthly Salary Credit.
Step 3: Calculate the PhilHealth premium. Apply the current contribution rules to the employee’s applicable compensation base, then identify the employee’s share.
Step 4: Deduct the Pag-IBIG contribution. Calculate the employee’s mandatory membership contribution using the applicable rate and compensation ceiling.
Step 5: Determine withholding tax. Calculate taxable compensation and apply the appropriate BIR withholding tax table for the payroll period. Account for relevant non-taxable earnings and allowable adjustments.
Step 6: Subtract other applicable deductions. Include loan amortizations, salary advances, or other lawful and authorized deductions that apply to the employee.
Step 7: Calculate net pay. Subtract the total deductions from gross earnings to determine the final amount payable to the employee.
Example of Take Home Pay Calculation
For an employee with a ₱30,000 monthly basic salary – gross ₱360,000 – the mandatory deductions are SSS, PhilHealth, Pag-IBIG, and withholding tax. Assuming no other loans or authorized deductions, the calculation is as follows.
Deduction
Computation
Employee Deduction
SSS
5% of ₱30,000 MSC
₱1,500.00
PhilHealth
2.5% of ₱30,000 basic salary
₱750.00
Pag-IBIG
2% of ₱30,000, capped at ₱10,000 fund salary
₱200.00
Withholding tax
15% of taxable income over ₱250,000 annually
₱1,007.50
Total deductions
₱3,457.50
Take-home pay
₱30,000 – ₱3,457.50
₱26,542.50
5. How Does Your Net Take Home Pay Affect Pag-IBIG Loans?
Your net take home pay affects how much you may be eligible to borrow from Pag-IBIG Fund because it helps determine whether you can afford the monthly loan repayments after existing deductions.
When evaluating certain Pag-IBIG loans, the Fund considers your repayment capacity alongside other factors, such as your accumulated savings, outstanding loan balances, and the amount you are requesting.
Official Pag-IBIG loan application forms state that the loanable amount may be limited if the proposed repayment would bring your net take-home pay below the applicable minimum requirement.
Also, Pag-IBIG does not set one fixed peso amount for the minimum net take-home pay (NTHP) for all borrowers. Instead, your loan is limited to an amount whose monthly payment will not push your NTHP below the minimum required by the General Appropriations Act (GAA)
Example: How Net Pay Affects Your Pag-IBIG Loan
Here is the example of Pag-IBIG loan, suppose two employees earn the same gross monthly salary of ₱30,000 but have different existing financial obligations.
Payroll Details
Employee A
Employee B
Gross monthly salary
₱30,000
₱30,000
Statutory contributions and tax
₱3,500
₱3,500
Existing loan repayments
₱500
₱2,500
Net pay before a new loan
₱26,000
₱24,000
If both apply for a Pag-IBIG loan, Employee A has ₱2,000 more monthly income remaining before the proposed loan repayment. Depending on the applicable loan rules and other eligibility requirements, Employee B may have less room for additional repayments.
6. Automate Every Net Pay Calculation with ScaleOcean Atlas
The more a business expands, the more complicated it becomes to manage payroll. HR teams have to deal with a wide variety of salary structures as well as overtime, leave, or tax withholding. These calculations are extremely time consuming and can be error prone.
In addition, HR departments can also take advantage of a Human Resource system that can automate tasks and streamline documents in a matter of seconds. The HRIS module of ScaleOcean Atlas is one of the most reliable systems that you can trust.
It is designed to be an ERP system which is linked to HR and payroll workflows and other business operations. The HRIS and payroll software, powered by ScaleMind AI, streamlines repetitive HR tasks and ensures efficient record-keeping among departments.
You can schedule a consultation to explore how ScaleOcean Atlas can support your payroll processes and operational requirements. Some of its key capabilities include:
Automated Payroll Calculations: ScaleOcean Atlas simplifies the process of calculating recurring salaries based on specific payroll rules, employee compensation, and deductions.
AI-Powered HRIS Automation: With the assistance of ScaleMind AI, ScaleOcean Atlas can help streamline routine HR administrative tasks and analyze HR data, enabling teams to invest less time in manual work.
Attendance and Overtime Tracking: By connecting attendance data with payroll workflows, with ScaleOcean Atlas businesses can account for working hours, overtime, and applicable adjustments more consistently.
Payroll Deduction Management: HR teams can organize deductions for SSS, PhilHealth, Pag-IBIG, withholding tax, and applicable loan repayments based on configured rules and current requirements.
Integrated Business Operations: Beyond payroll, ScaleOcean Atlas connects business processes through its ERP platform, helping teams reduce data silos and repetitive administrative work.
Streamlined HR Workflows: By reducing manual data handling, ScaleOcean Atlas helps HR teams manage recurring payroll activities more efficiently and focus on employee support.
In Conclusion
Knowing net take home pay can give employees a better idea of how much they make before taxes and how much they take home. For the Philippines, gross earnings, forced deductions, withholding tax and other deductions are taken into account.
Also, the employee can check each item on the pay slip, it will help in loan planning and budgeting. For employers, the calculations are correct, and the payroll records are clear, which helps to develop their trust in the employer and minimize unnecessary administrative work.
As payroll requirements become more complex, businesses can start to look for an alternative system to reduce manual tasks. With ScaleOcean Atlas, HR teams can streamline payroll workflows and organize employee records in one system.
Book a consultation schedule now to optimize your business HR administration and payroll process that can reduce human error and miscalculation.
FAQ:
1. What is net take-home pay?
Net take-home pay is the last paycheck amount that an employee receives after tax obligations, mandatory contributions and other deductions have been taken from their gross pay.
2. What is the difference between net pay and take home pay?
No, they are equal, both mean the amount that an employee receives after all required and voluntary deductions (e.g. taxes and contributions) are taken from the gross pay.
3. How do you calculate net take home pay in the Philippines?
Net take-home pay in the Philippines is equal to the employee’s total gross salary minus SSS, PhilHealth contributions, Pag-IBIG contributions, BIR withholding tax and other authorized deductions.
4. Is net pay the same as basic salary?
No. Basic salary is the fixed pay agreed upon before any additions or deductions. Net pay is the final amount an employee receives after adding total earnings and subtracting all deductions.
5. Does 20k salary have tax?
Generally, no. A ₱20,000 monthly salary equals ₱240,000 yearly, below the ₱250,000 annual taxable-income threshold under the TRAIN Law, so it normally falls under the 0% bracket with no withholding tax, assuming no other taxable income.



 Key Takeaways